For the first time in roughly twenty years, Google has a competitor operating at internet scale. But the most interesting part of the story is not that Google is disappearing. It is that the total number of questions people ask machines has exploded—and AI has created an entirely new layer of demand alongside search.
I have been doing SEO since the early 2000s, when I was trying to grow a real-estate business without becoming a pushy salesperson. Search made sense because that was where people were already looking. For roughly two decades, that effectively meant Google.
I did not originally set out to write this article. I was trying to answer a product question while building friendlier mobile versions of Google Keyword Planner and Search Console: how big is the query market now that AI assistants exist, and who actually owns it?
Nobody publishes one clean number for “all searches + all AI prompts.” So I built a directional model from disclosed search volumes, disclosed AI usage, user counts where companies do not disclose prompt volume, and a clearly stated set of assumptions.
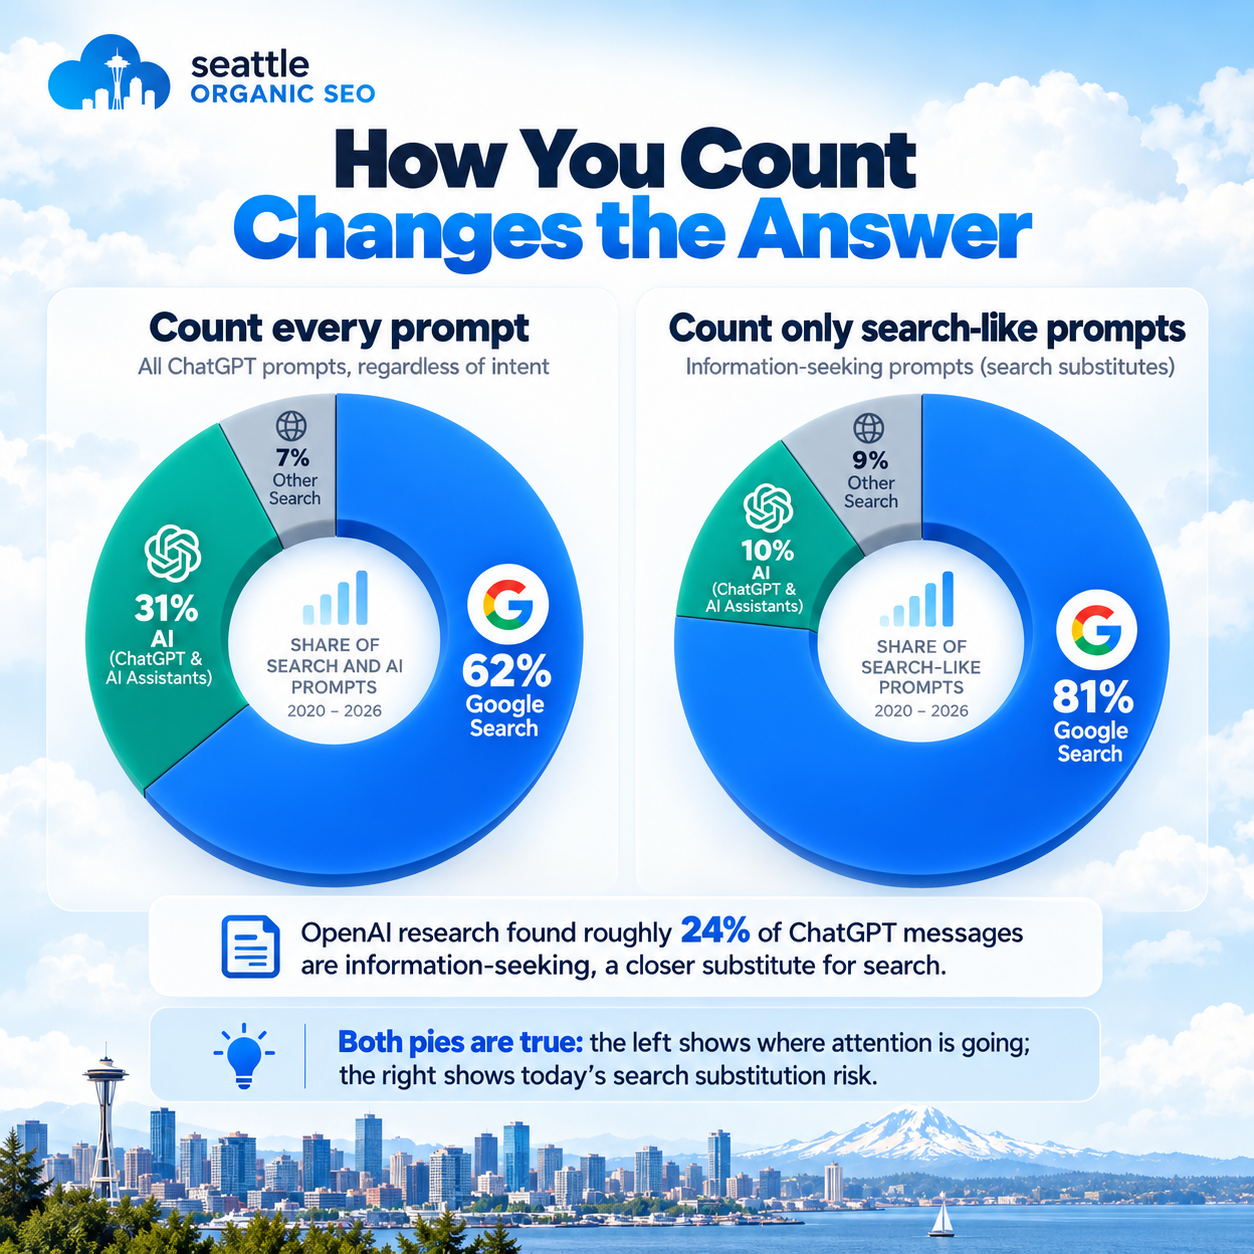
The headline: by our modeled count, AI assistants now handle roughly 31% of the questions and prompts people type into machines each day. But only a fraction of those prompts are true substitutes for web search. That distinction changes almost everything.
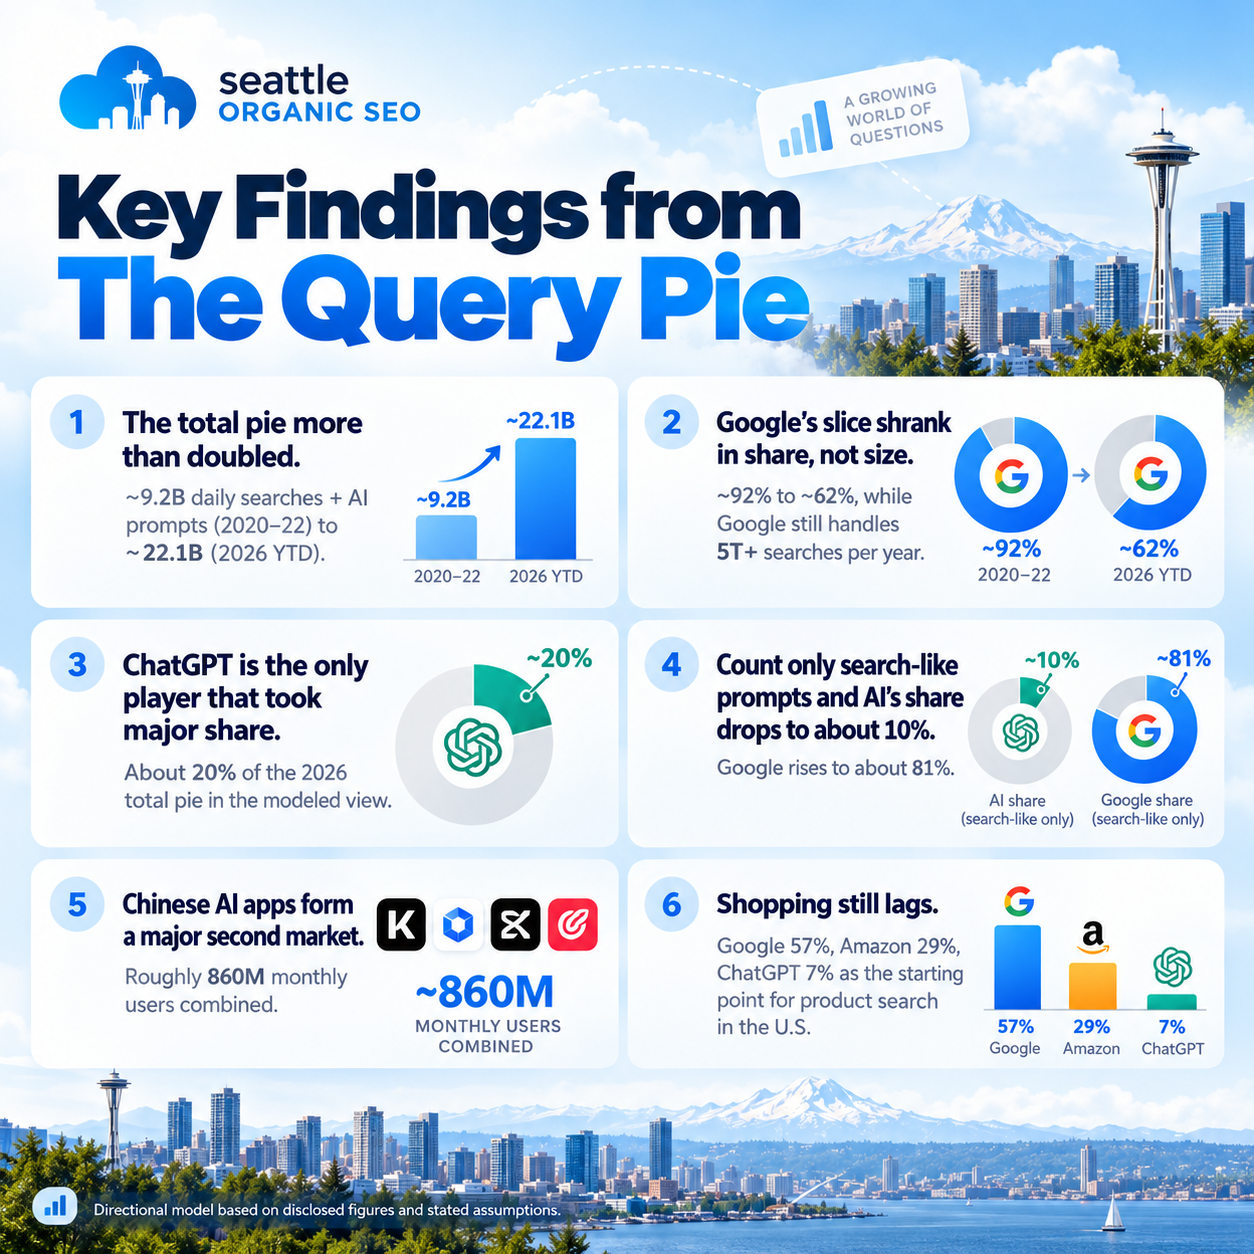
The six findings that matter most
The pie, year by year
Google did not suddenly collapse. What changed was the denominator. AI created billions of additional interactions that did not exist in the old search market.
2020–22
2023
2024
2025
2026
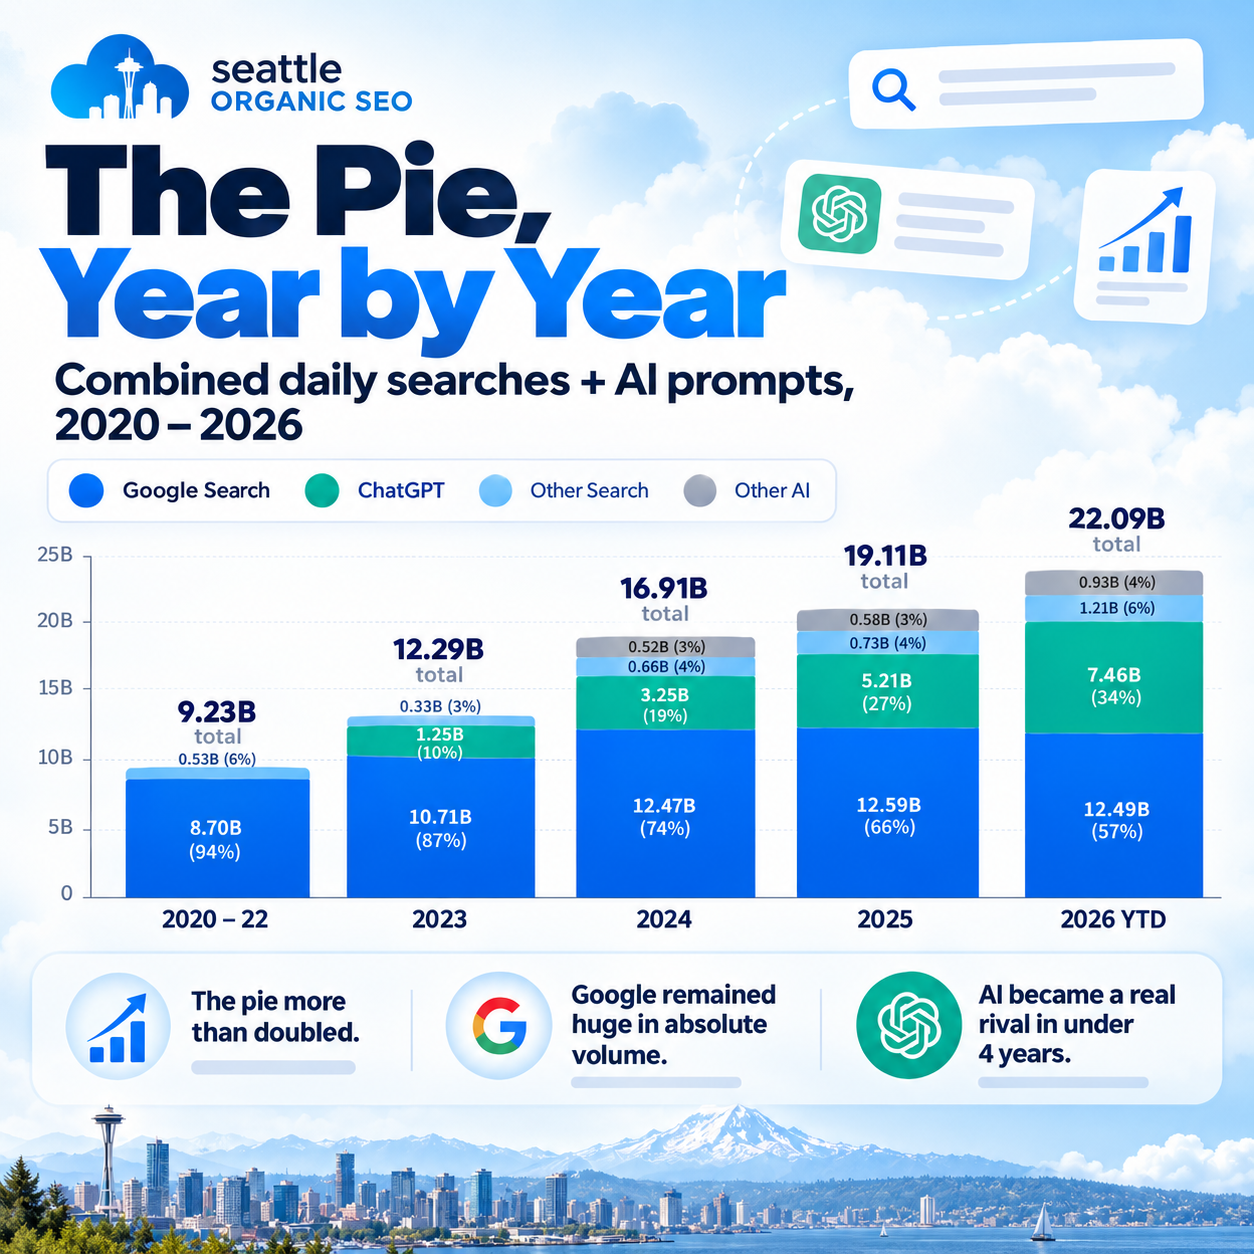
This is the point most “Google is dead” takes miss: Google’s slice shrank because the overall market expanded. Its absolute search volume did not disappear.
How you count AI changes the answer
A prompt is not automatically a search.
People use ChatGPT to write emails, draft code, tutor children, brainstorm, summarize documents, generate images and plan meals. OpenAI’s own usage research found that roughly 24% of ChatGPT messages were information-seeking—the category its researchers described as a closer substitute for web search.
Count every AI prompt
~31% AI
This is the better measure of where digital attention and machine-mediated work are going.
Count search-like AI prompts
~10% AI
This is the more relevant measure of how much of Google’s core information-retrieval job has shifted today.
Both views are useful. They answer different questions.
The first asks: Where are people spending their question-asking attention?
The second asks: How much traditional web-search behavior has AI actually replaced?
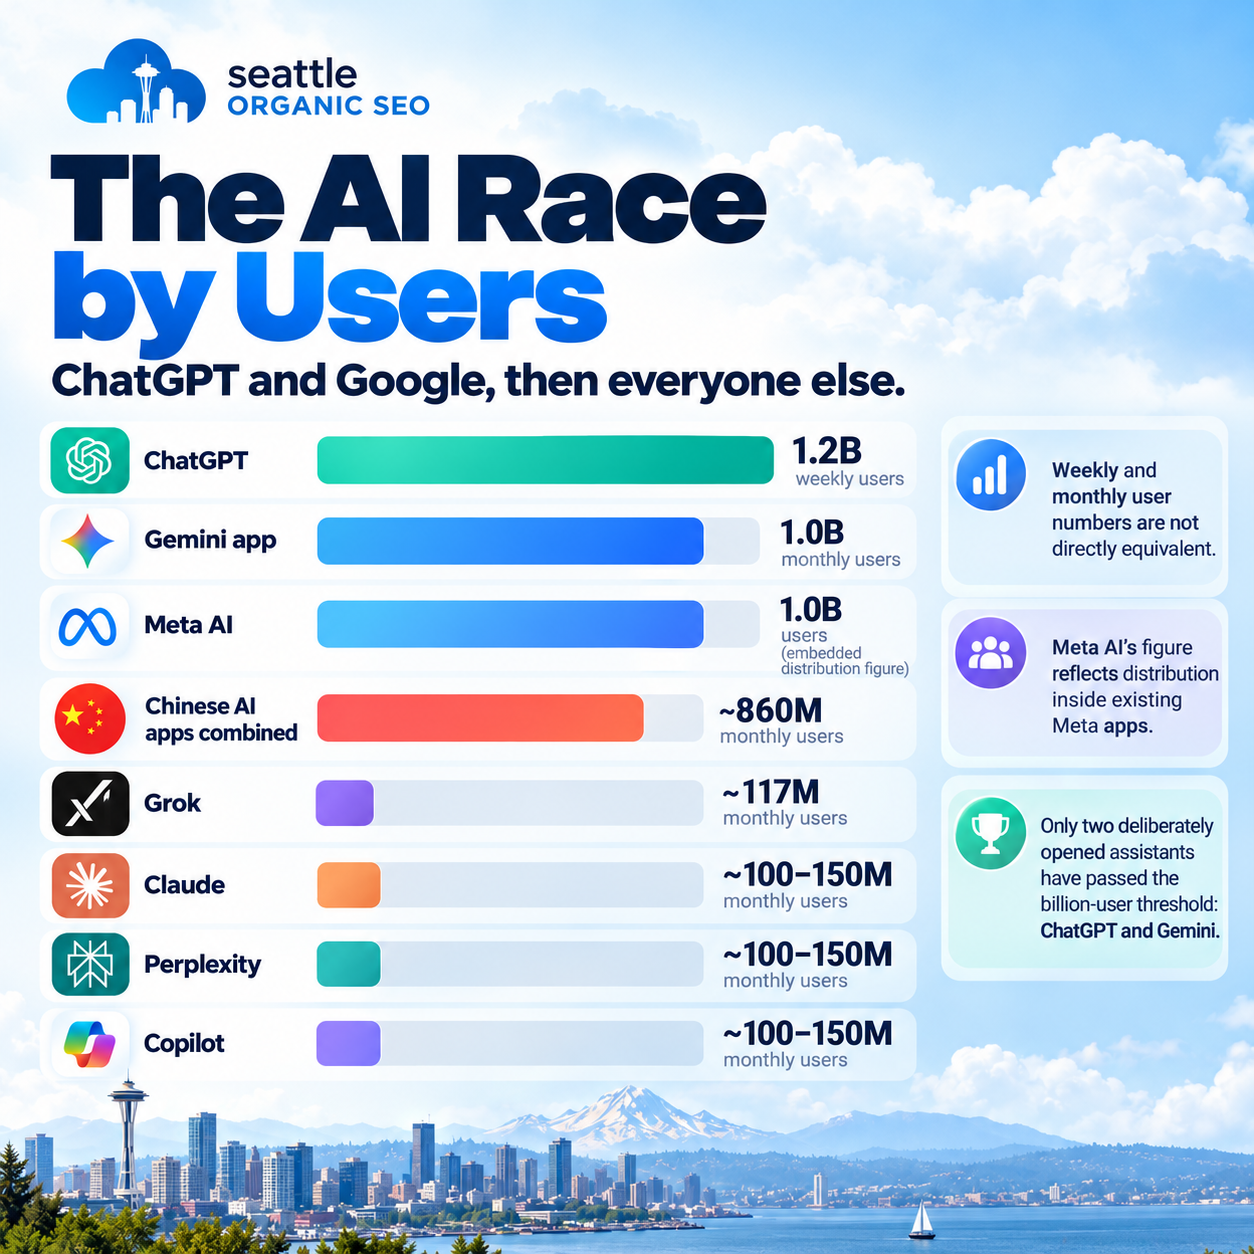
The AI race by users: ChatGPT and Google, then everyone else
By users, the race is already surprisingly concentrated.
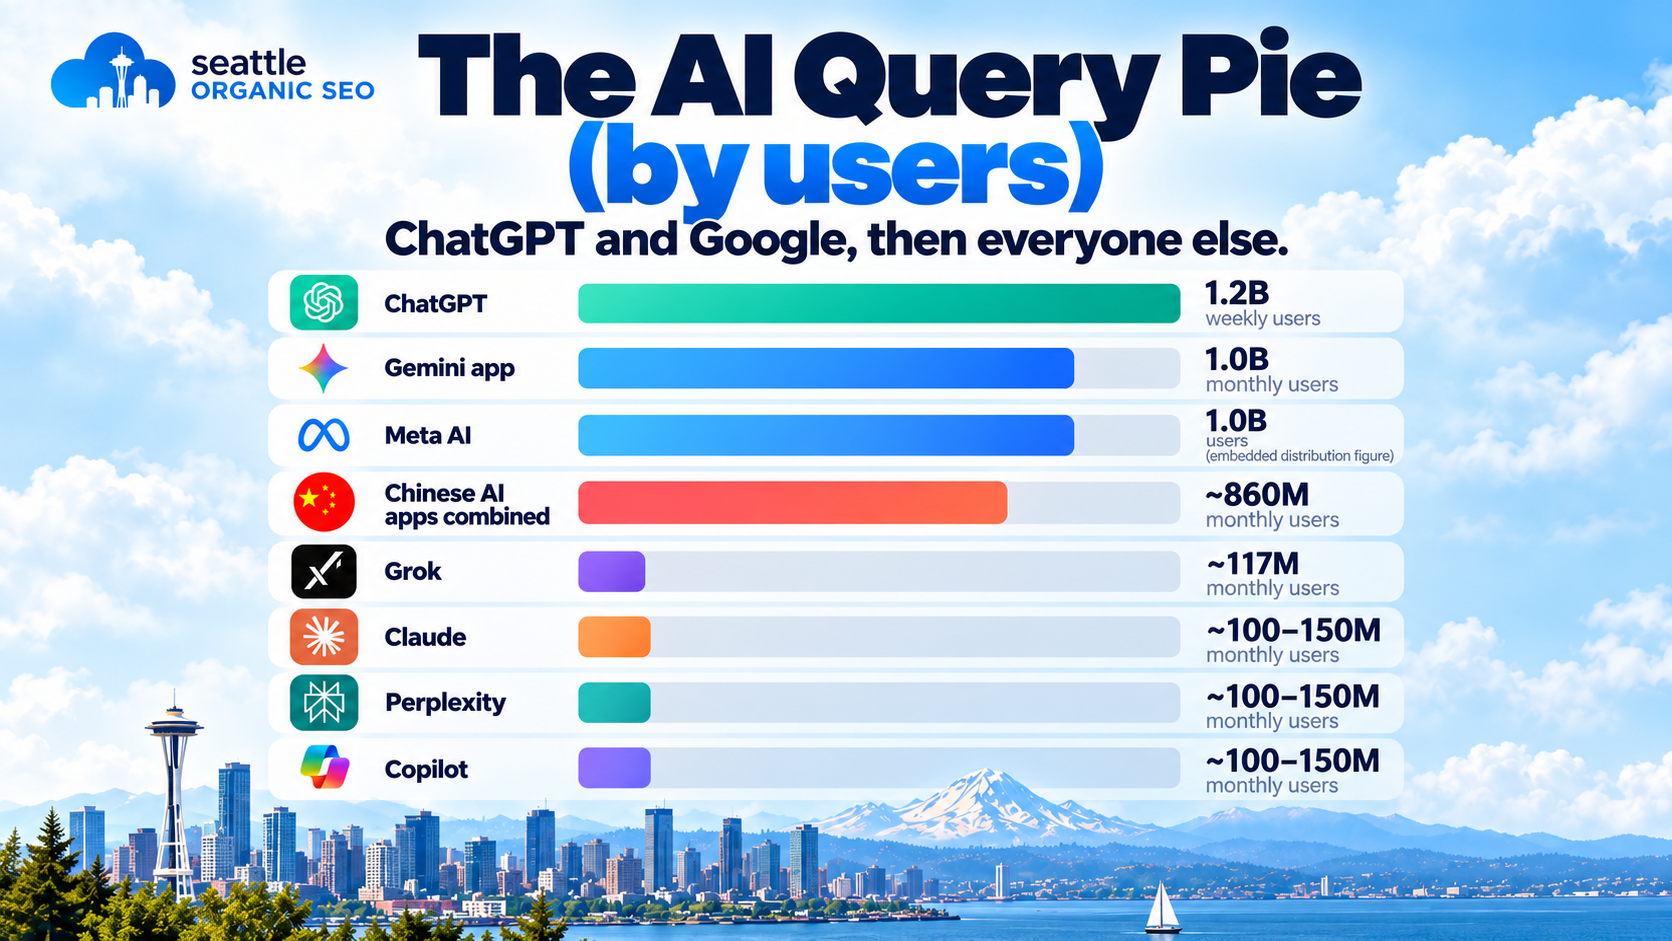
ChatGPT has reached roughly 1.2 billion weekly users. Google’s Gemini app has passed 1 billion monthly users. Those metrics are not directly equivalent—weekly users are a harder threshold than monthly users—but both products now operate at a scale that would have been difficult to imagine for standalone AI assistants just a few years ago.
Meta AI also reports roughly a billion users, but that number reflects distribution inside WhatsApp, Instagram, Facebook and Messenger. It is not the same thing as one billion people intentionally opening a dedicated AI assistant.
Below that top tier, the Western challengers are much smaller but growing quickly. Grok, Claude, Perplexity and Microsoft Copilot sit around the hundred-million-user range in the figures used for our model.
The honest headline is not “ChatGPT beat Google.” ChatGPT beat Google’s standalone AI app to this level of engagement. Google Search itself is still vastly larger, and Google’s AI Overviews and AI Mode are embedded inside the search product people already use.
That distribution advantage matters. AI Overviews reach billions of people, and AI Mode has crossed the billion-user mark. Google did not simply watch the shift happen from the sidelines—it placed AI inside the interface where billions of search behaviors already occur.
Still, something historically important happened: for the first time in roughly twenty years, another company built an information product at Google-like scale. Bing never got close. ChatGPT did it in under four years.
China is a separate AI race
Western marketers tend to frame AI as ChatGPT versus Gemini, with Claude, Perplexity, Grok and Copilot competing for the rest. That view misses a second enormous market.
In the data used here, Chinese AI apps such as Doubao, Qwen, DeepSeek, Yuanbao and Kimi add up to roughly 860 million monthly users. Doubao alone is around 382 million monthly users in the figures included in our model.
If your business sells primarily in North America, that may not change your marketing plan tomorrow. If you operate internationally, it absolutely should change how you think about the competitive landscape.
Shopping is the slowest behavior to move
General information discovery is shifting faster than commerce discovery.
In the 2026 U.S. shopping research included in this analysis, roughly 57% of shoppers start product search on Google, another 29% start on Amazon, and only around 7% begin with ChatGPT.
That means the immediate ecommerce fight is still Google versus Amazon.
But there is an important second layer: roughly 60% of respondents had used AI for shopping research at least once, while 44% said they search less because they can ask an AI. So AI has not won the starting point, but it is increasingly joining the consideration process.
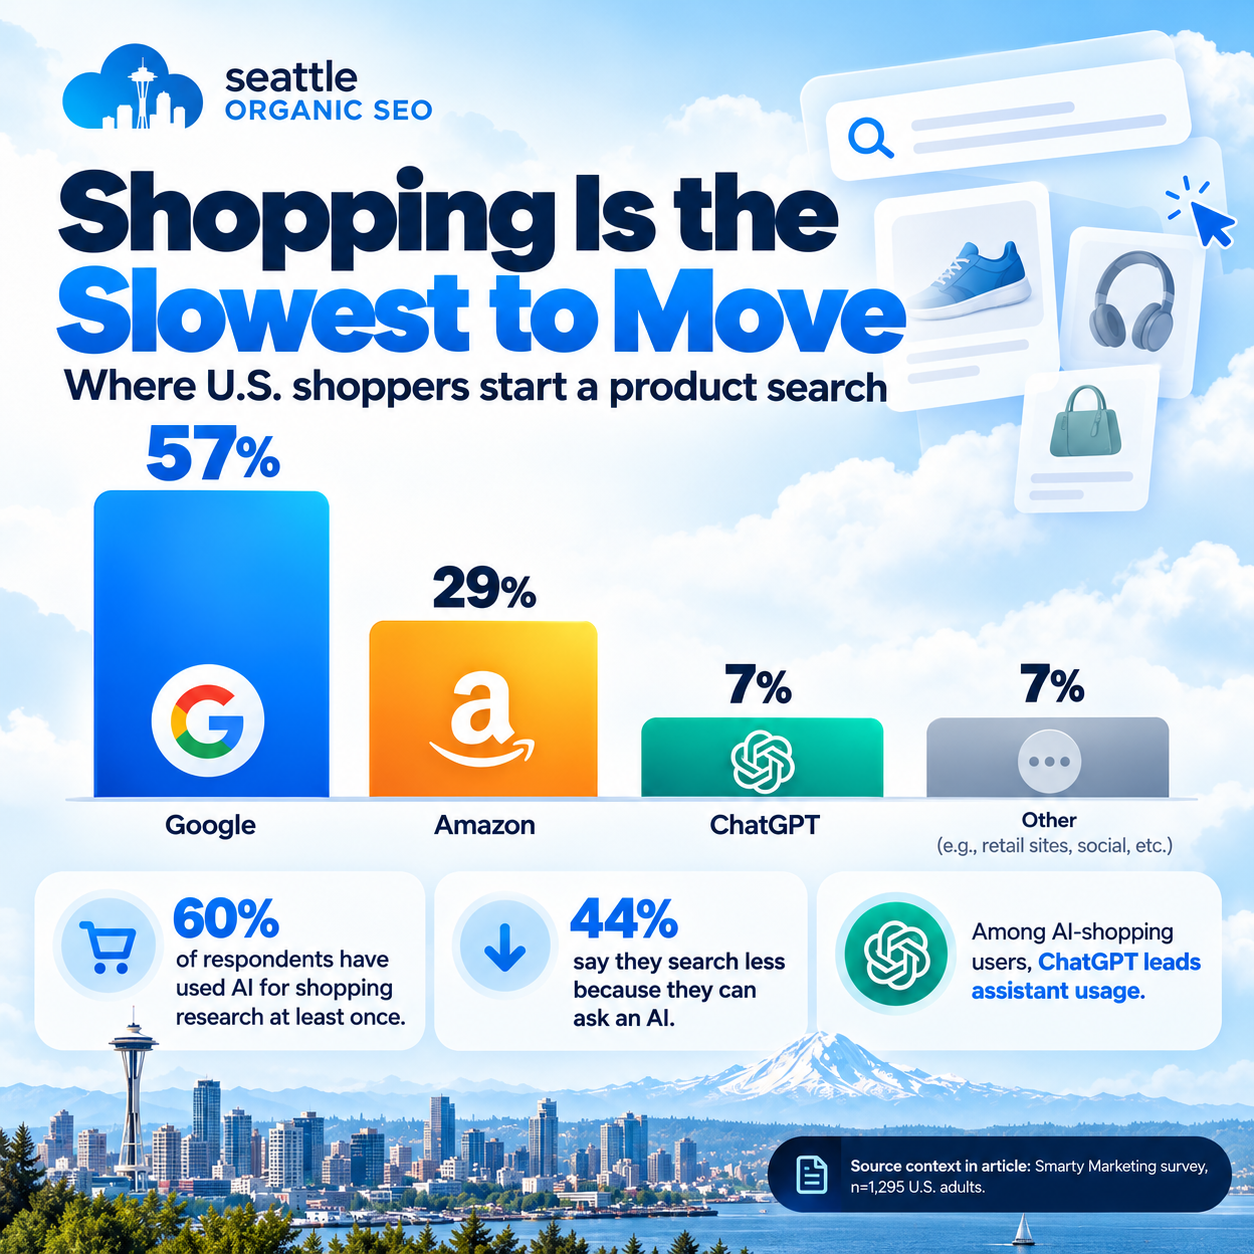
Among AI-shopping users in the source data, ChatGPT led assistant mentions at 48.4%, followed by Gemini at 27.9%, Microsoft Copilot at 9.9%, Claude at 6.8%, Perplexity at 3.8%, and other assistants at 3.2%.
Why AI did what Bing could not
Bing spent two decades trying to compete with Google and never took much more than a few points of worldwide search share.
That was not because Microsoft lacked money, engineers or distribution. It was because Bing mostly offered the same basic job: type a query, receive a ranked list of links.
AI changed the job.
For years, Google gave us the sources and left the synthesis to us. Search for something complicated and the user still had to open tabs, scan pages, compare claims, reconcile differences and decide what mattered.
AI compresses that middle step. It reads, summarizes, compares and recommends.
That convenience is why the shift matters more than the interface. People do not move simply because a new search box is prettier. They move when the new product removes work.
We have seen this type of behavioral shift before. In the early 2000s, email and search felt like the defining activities of the internet. Social media looked secondary—until it was not. The channel that appears untouchable in one era is not guaranteed the next one.
What marketers and business owners should do now
The answer is not to abandon Google. The answer is to add a second question to your search strategy:
When a customer asks an AI about the problem you solve, are you part of the answer?
- Do not abandon SEO. In our search-equivalent model, Google still represents roughly 81% of search-like demand. It also remains the starting point for 57% of U.S. product searches.
- Audit AI visibility. Ask ChatGPT, Gemini, Claude and Perplexity the ten or twenty questions customers most often ask before hiring or buying. Record which companies get mentioned and which sources get cited.
- Create material worth citing. Clear answers, original research, first-party data, useful comparisons, real reviews and independent mentions give AI systems something stronger to retrieve than generic copy.
- Do not optimize for one model. ChatGPT leads today, while Gemini has grown extremely quickly. Build for a shelf of assistants and answer engines rather than trying to “rank #1 in ChatGPT” as though it were one fixed SERP.
- Watch geography. International businesses need a different map than U.S.-only companies. The Chinese AI ecosystem is already enormous.
This is also why we increasingly think of SEO and GEO/AEO as one connected discipline. Google’s classic results, AI Overviews, AI Mode, ChatGPT, Gemini, Perplexity and other assistants are drawing from overlapping information ecosystems.
At Seattle Organic SEO and GrowYoo, we are building toward that reality—starting with mobile tools that make traditionally awkward Google workflows such as Keyword Planner and Search Console easier to use, and moving toward prompt-level visibility.
Methodology: how we built the Query Pie
No company publishes a clean “share of all searches and AI prompts” report. Every number in this model therefore has to be interpreted as a directional estimate, not an audited census of human curiosity.
Use the model to understand the direction and relative scale. Do not pretend a 20.2% estimate is meaningfully different from 19.7% when some underlying platforms do not disclose prompt volume at all.
Google search volume
We use roughly 8.5 billion searches per day as the 2020–22 baseline, a widely cited third-party estimate. From 2024 forward we use 13.7 billion searches per day, derived from Google’s disclosure of more than five trillion searches annually. We hold 2025 and 2026 at 13.7 billion as a conservative floor, even though SparkToro/Datos estimates cited in the research are higher.
Bing and other search engines
We scale other traditional search engines from Google’s volume using each year’s worldwide StatCounter search-share figures.
ChatGPT
The model uses disclosed prompt/message figures where available: approximately one billion prompts per day by late 2024 and roughly 2.6 billion per day in the 2025 data used here. For 2023 and 2026, where the model relies on weekly user counts, prompt volume is estimated from users and observed prompts per user.
For 2026, that produces roughly 4.46 billion daily ChatGPT prompts. If you instead hold ChatGPT to the last official lower daily figure used in the research, its share drops to roughly 12.4% and total AI share to roughly 24.8%.
AI assistants without disclosed daily prompt volume
For Gemini app, Claude, Copilot and the Chinese AI apps, the model uses monthly users multiplied by one prompt per user per day. That is deliberately conservative relative to ChatGPT’s observed usage intensity.
Search-equivalent AI
To estimate how much AI actually substitutes for search, each AI prompt is counted at 24%—the information-seeking share in the OpenAI usage study included in the source research.
What is not counted
The model excludes Google AI Overviews and AI Mode as separate prompts because those experiences sit inside Google Search. It also does not include Amazon onsite search, YouTube search, social-platform search or API traffic.
The modeled daily volume
The table below is intentionally presented as a set of year cards rather than a wide spreadsheet. That keeps the data readable on desktop, tablet and mobile without forcing horizontal scrolling or creating a second mobile-only copy of the same numbers.
2020–22
2023
2024
2025
2026 YTD
Cross-check: the source research notes a Semrush-cited estimate placing ChatGPT at 17.6% of total digital queries in 2026, between the conservative floor and the higher modeled ChatGPT share used here.
The bottom line
Google is not dead.
That is the least interesting conclusion you can draw from the numbers.
The more important conclusion is that the market itself changed. Billions of daily interactions now happen in a category that did not exist at meaningful scale four years ago. ChatGPT did not need to steal every Google search to matter. It expanded what people expect a machine to do when they ask a question.
Google responded by putting AI directly inside Search. ChatGPT kept expanding as a standalone destination. Gemini became a billion-user app. New assistants emerged in the West, while an enormous parallel market developed in China.
For marketers, that means “search strategy” can no longer mean only rankings in ten blue links.
Keep winning on Google. But start measuring whether your company is part of the answers people receive when they stop searching and start asking.
Sources used in the model
- Google: 5 trillion+ searches per year — Search Engine Land
- Google ~8.5B searches/day pre-2024 estimate — HubSpot
- Worldwide search share by year — StatCounter / MPG ONE compilation
- ChatGPT 2.5B prompts/day; Google 13.7B–16.4B/day — TechCrunch
- OpenAI/NBER “How People Use ChatGPT” — information-seeking share
- ChatGPT 18B messages/week — Biz New Orleans
- Gemini app passes 1B monthly users — Unite.AI
- Gemini user history; AI Overviews / AI Mode users — Carly
- Meta AI user figures — Engadget / TechCrunch
- Perplexity query history — Backlinko
- Grok user and query figures — cited SpaceX S-1 / source research
- Doubao, Qwen, DeepSeek user figures — QuestMobile / Second Talent
- U.S. product-search starting point — Smarty Marketing, 2026
- Answer-engine product-discovery adoption — Forrester
- ChatGPT share of digital queries — SEOProfy / Semrush-cited data
- Google Search user estimate — Exploding Topics
- Google I/O 2026 product user scale — source research
- ChatGPT 1.2B weekly users — TechnologyChecker citing OpenAI
- Comscore March 2026 U.S. chatbot rankings — GlobeNewswire / Taiwan News
- Copilot user estimates across surfaces — Presenc AI
Because several companies report weekly users, others monthly users, and some report prompt/query volume rather than users, the figures should not be treated as perfectly apples-to-apples. The methodology above explains how those disclosures were normalized into a directional model.
Are you visible in AI answers yet?
Seattle Organic SEO has spent more than 16 years helping businesses compete in Google. Now we are extending that work into GEO, AEO and AI visibility—without pretending the fundamentals of SEO stopped mattering.